
How Roof Insurance Claims Work in Washington and Idaho
A roof claim is not complicated, but it punishes people who do things out of order. The sequence below is the one that gets claims approved.
What insurance covers, and what it never covers
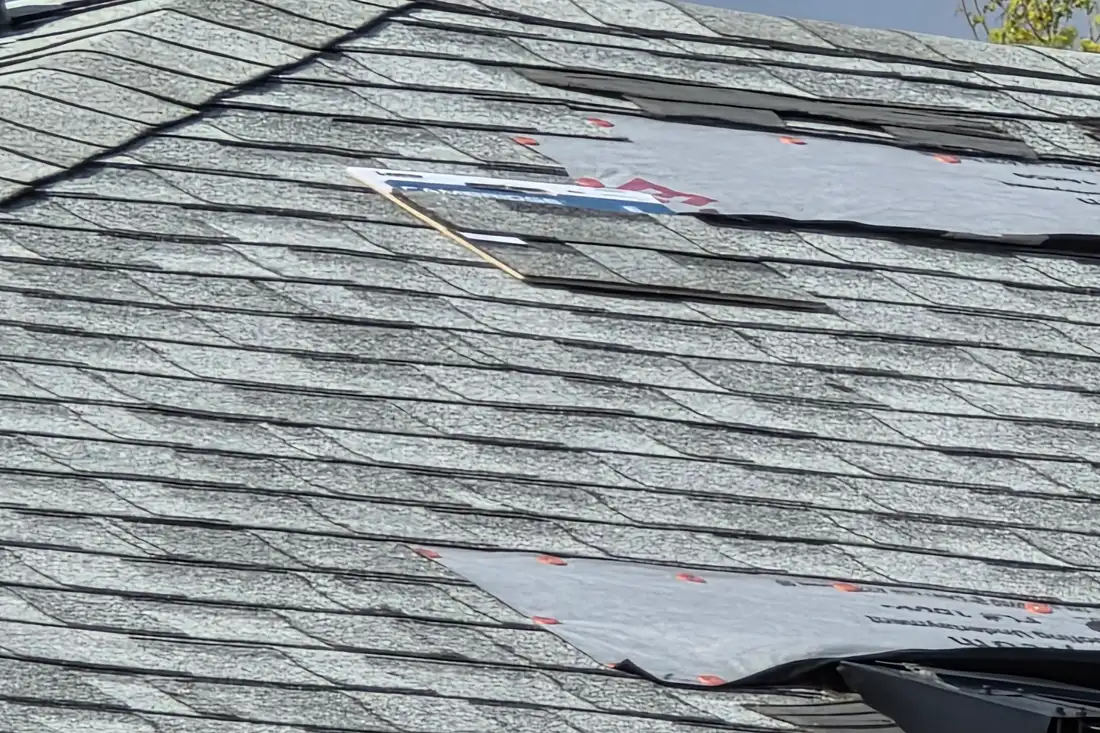
Policies cover sudden damage from a specific event: wind lifting or removing shingles, hail bruising the mat, a limb or tree striking the roof, the weight of an unusual snow load. What they do not cover is age. A worn roof that finally leaks was not damaged by a storm; it finished its life. Adjusters are very good at telling the difference, and no amount of arguing will change a granule-worn twenty-year-old roof into storm damage.
In between is the grey area that decides most claims: an old roof that a storm finished off. This is where documentation matters, and where a contractor who knows what an adjuster looks for is worth having.
The order to do things in
1. Stop the damage first
If water is entering the house, get it tarped. Most policies treat reasonable emergency measures to prevent further damage as covered, and doing nothing while waiting for an adjuster is the one thing that can reduce your payout. We do emergency tarping seven days a week; see emergency roofing.
2. Photograph everything, before it is cleaned up
Shingles on the ground, the dented gutter, the downed limb, the water stain on the ceiling, the wet insulation in the attic. Note the date of the storm. If neighbors have damage, that helps: it establishes a storm event rather than a maintenance issue.
3. Call your insurer and open the claim
You do not need a contractor to open a claim, and you should not delay to get one. Give them the date of loss and a description of the damage. You will get a claim number and, usually, an adjuster appointment within a week or two.
4. Get a contractor out before the adjuster
This is the step people skip. If your contractor has already measured the roof, identified the damage and written a scope, the adjuster is inspecting a known quantity instead of forming a first impression alone. It is much easier to agree on a scope than to dispute one later.
5. Meet the adjuster on the roof
We meet adjusters on site as a matter of course. The adjuster sees things from the ladder; a roofer who has been on thousands of roofs sees the same thing and can point out what is not obvious. Missing that meeting is how legitimate damage ends up excluded from the initial scope.
6. Read the scope, then supplement if needed
An approved claim comes with a scope: a line-by-line list of what the insurer will pay for. It is common for the first scope to miss something real, such as ice and water shield, a section of decking, or code-required ventilation. That is not bad faith, it is a first pass. A supplement is the normal, expected way to correct it, and we prepare those.
Deductible, ACV and RCV, in plain terms
Your deductible comes off the top and is your share, whatever the final number is. Replacement cost value (RCV) pays what it costs to replace the roof today. Actual cash value (ACV) pays replacement cost minus depreciation for the age of the roof, which on an older roof can be a large difference. Many policies pay ACV first and release the depreciation once the work is complete and invoiced. Ask which one you have before you sign anything.
Things that will sink a claim
- Waiting weeks to report it, then having no record of the storm
- Letting a friend with a hammer do temporary repairs and leaving no photographs
- Signing an assignment of benefits that hands the claim over to a contractor
- Accepting the first scope without a contractor review
- Paying a deductible to a contractor up front, in cash, before any work
What we do, and what we do not
We inspect and document the damage, prepare a scope in the format insurers expect, meet your adjuster on the roof, and supplement when the approved scope misses something. We do not inflate claims, and we will tell you if your damage is not worth a claim, because a claim on your record costs you more than it is worth when the roof simply aged out.
Call (509) 404-4444 or get in touch and we will look at it this week. More on our process at insurance claim help.
Want a roofer to look at it in person?
ALPHA LLC inspects roofs across Spokane Valley, Spokane and North Idaho. The inspection and the written estimate are free.